This article is from the Australian Property Journal archive
TRANSPORTATION logjams have been joined by limited spare domestic production capacity, low inventories, higher input costs and labor challenges in turbo-charging supply chain pressures that will not relent until the second half of next year.
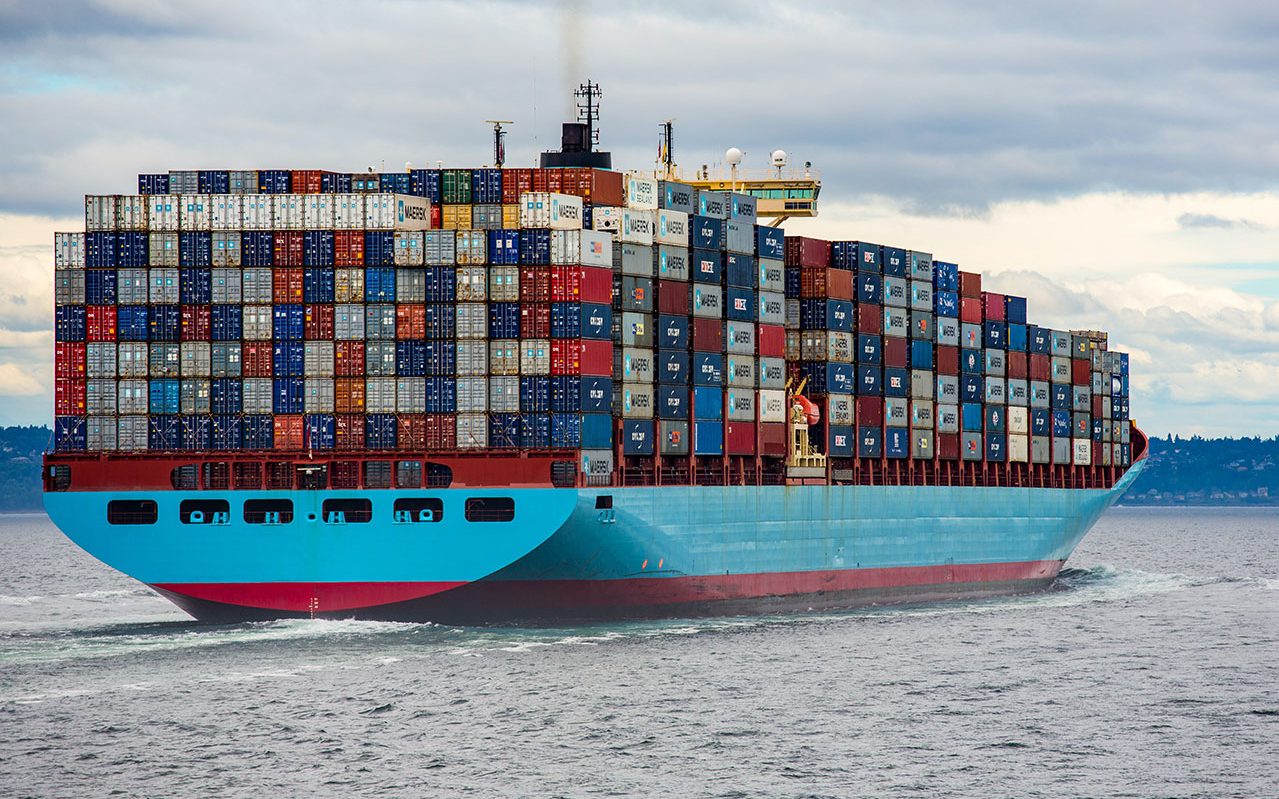
A BIS Oxford Economics research note says ocean freight is a chokepoint, with record inbound cargo shipments driving shipping costs up over 400% since the beginning of the pandemic.
Meanwhile, the shipping containers full of goods are being left at seaports for up to two weeks in the United States before starting their trucking trip to their destination. The trucking industry moved 75% of total freight across the country and wait times are up from three to four days prior to COVID.
Independent maritime research consultancy Drewry data shows the World Container Index has hit US$10,083.84 per 40ft container – a 309% increase from 2020.
Manufacturing capacity utilization was 76.7% in August, higher than the 2015-19 average and less than close to the highest reading of the past two decades.
“Slack is minimal in durables and nondurables production, with Covid shining a light on the fact that US production capacity hasn’t risen since 2000,” BIS Oxford Economics lead US economist Oren Klachkin said.
Production costs have skyrocketed by 35 to 55%, most notably for raw materials used in durables and nondurables manufacturing due to significant shortages and strong demand.
“The economy today faces the greatest imbalance between raw materials and finished goods in two decades.
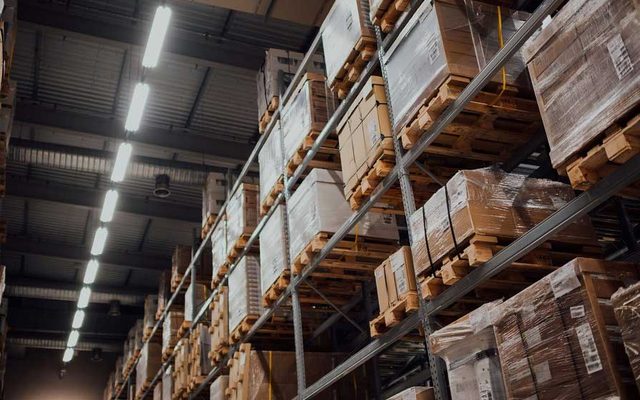
“Inventory restocking normally coincides with business cycle upturns, but COVID has decidedly broken that relationship. Nearly 75% of manufacturing subsector inventories are leaner relative to sales currently than before COVID.”
Sass J-Baleh, head of industrial and logistics research at CBRE, said in a new report that Australia’s retail inventory sales ratio prior to 2020 had been trending down for 30 years, reflecting a “just in time” model.
“Global supply chain disruptions have highlighted the need for retailers, particularly those using an online sales platform, to hold more inventory to minimise fulfillment delays, which is driving greater demand for industrial and logistics space.”
J-Baleh also noted the rise in inventory requirements in the US in line with the growth of e-commerce penetration since 2012 should be mirrored in Australia in the next few years.
With increasing inventory requirements both capital and rental value growth are being placed under upwards pressure.
Premier Investments, owner of retail brands including Peter Alexander, Smiggle, Just Jeans, Dotti, Jay Jays and Portmans, unveiled a full-year profit that almost doubled to $271.8 million that it owed much of to bigger margins due to less discounting. The company again touted the investment made in its own inventory and ownership of its distribution centre, allowing to have more control of stock supply.
An Asialink Business report supported by Toll Group said the global network is facing unprecedented disruption and strain, businesses in Australia and Asia need to rapidly transition to equip their supply chains for current and future challenges.
The growth in online shopping and the resulting logistics requirements means Sydney is now estimated to need another 720,000 sqm of logistics space over the coming for years to keep up with demand.
The Asia Pacific region accounted for 62% of all e-commerce sales globally in 2020, according to AsiaLink report, and businesses across Australia and Asia need to invest in building resilient supply chains that can keep pace with the explosion of e-commerce and changing consumer expectations around sustainability.
Meanwhile in Australia ongoing government delays in providing a reopening plan could cost the supply chain industry more than $10 million each day, Ports Australia has warned.
Ports Australia’s CEO Mike Gallacher said the longer the delays persist, these costs will inevitably be worn by the Australian people.
“We cannot see the resilience of the supply chain throughout the pandemic undone by a lack of planning especially as we head towards the first Christmas season out of COVID,”
Earlier this Gallacher said the fragility of the economy and the looming threat of a recession will be crystallised like never before if we see unprecedented shutdowns along the supply chain.
“We’ve seen moments of public hysteria throughout the pandemic like when toilet paper went flying off supermarket shelves at unprecedented rates, and that was when the supply chain was strong-functioning!
“We cannot afford to have this poorly planned… we appreciate government authorities are overwhelmed right now but that will be taken to a whole new level when panic ensues once again.” Gallacher said.
Back in the US, rising unfilled job vacancies, strengthening wage growth, and more overtime hours signal rising labor-related pressures, although BIS Oxford Economics finds that labor stress is relatively lower than other supply-side challenges.
And BIS Oxford Economics sees “a light at the end of the tunnel”.
“As vaccination rates rise in the US and overseas and demand slowly returns to pre-pandemic patterns, transportation logjams will clear, input costs will normalize, and production and hiring challenges will recede.
“Our latest macro and industry baseline projections assume supply-chain headwinds will weigh on activity until at least H2 2022. However, disruptions in certain sectors – such as the semiconductor chip shortage’s impact on automobile production – could last into 2023.
“Similarly, our global client base is concerned supply-chain headwinds could last beyond mid-2022.”