This article is from the Australian Property Journal archive
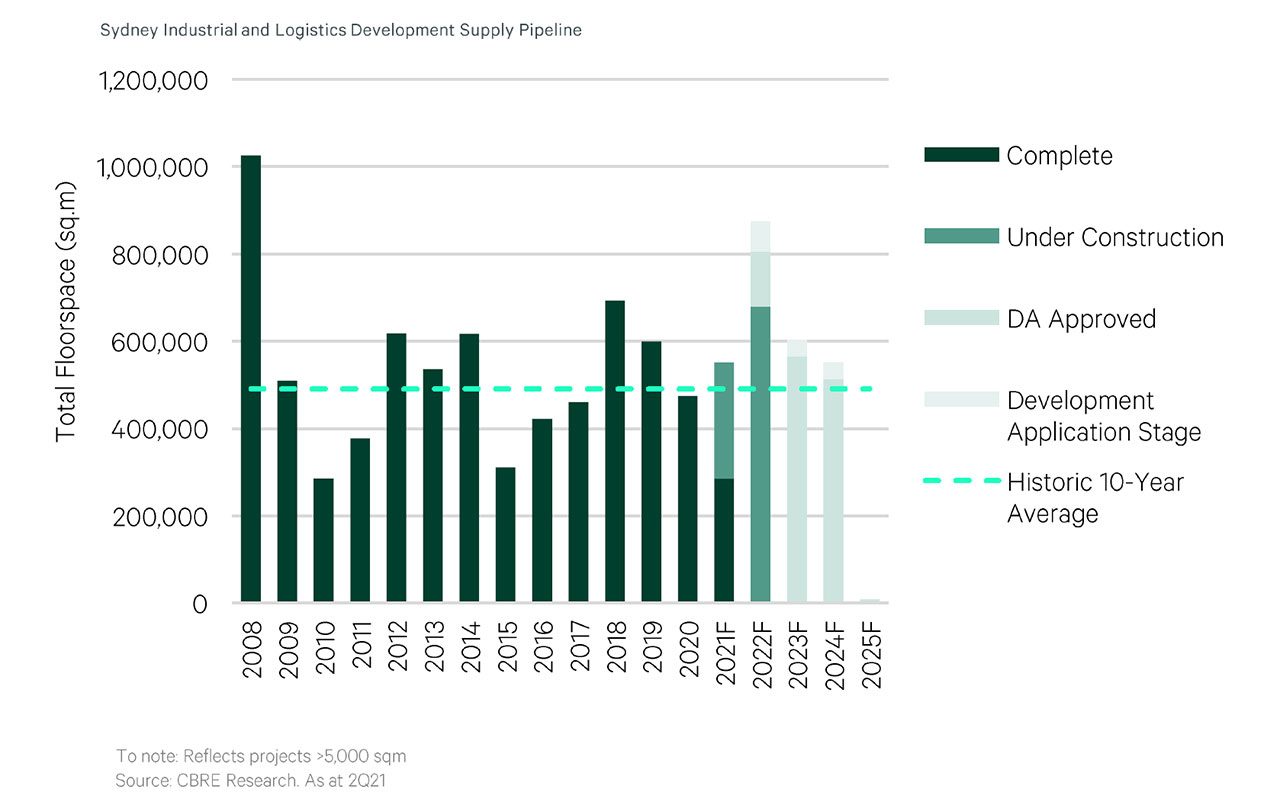
SYDNEY will need another 720,000sqm of logistics space over the coming for years to keep up with online retail demand.
According to CBRE’s Sydney Industrial & Logistics Land Supply report, limited industrial land supply in inner city Sydney, paired with e-commerce sales that have been significantly boosted by the pandemic and ongoing lockdowns, supply will need to climb by 37% compared to typical growth.
“Prior to 2020, Australia’s retail inventory sales ratio had been trending down for 30 years, reflecting a ‘just in time’ model,” said Sass J-Baleh, head of industrial and logistics research at CBRE.
“Global supply chain disruptions have highlighted the need for retailers, particularly those using an online sales platform, to hold more inventory to minimise fulfillment delays, which is driving greater demand for Industrial & Logistics (I&L) space.”
J-Baleh also noted the rise in inventory requirements in the US in line with the growth of e-commerce penetration since 2012 should be mirrored in Australia in the next few years.
With increasing inventory requirements both capital and rental value growth are being placed under upwards pressure.
This growth is underpinned by only 5% or 605-hectares of the 13,000-hectares of industrial zoned land in Sydney being undeveloped and serviced.
“This lack of land availability is particularly evident in Sydney’s inner precincts, which are becoming ever more sought after as ‘last mile’ hubs as e-commerce penetration rates rise,” added J-Baleh.
Of this undeveloped and serviced land, only 0.2% is located in Sydney’s north shore, while 43.4% is in the outer south west.
While 2.8% is in Sydney’s north, 9.3% in the central west, 2.5% in the south, 2.4% in the inner south west, 3.9% in the metropolitan west and 35.4% in the outer north west.
Of this land, precincts nearest to the CBD and airport have the least available and serviced land, with average land values in the south and north precincts more than twice that of the outer western precincts.
“Over the next 18 months we forecast further limits to the availability of undeveloped and serviced land in Western Sydney, with no availability expected in Sydney’s inner precincts over the medium term,” said J-Baleh.
Over the last decade, land absorption in Sydney has averaged 137-hectares each year, with leasing activity over the decade averaging 805,000sqm.
“Given Sydney’s limited development pipeline and lack of speculative activity, this is expected to drive rental growth rates and result in further land value appreciation over the short to medium term,” said Cameron Grier, Pacific regional director at CBRE.
According to Grier, any risk of oversupply brought on by new emerging serviced and zoned land corridors, including the Mamre Road precinct and Badgerys Creek, will be offset by this growing occupier demand.
“The I&L land market has well and truly been reset and traditional institutional developers are now willing to pay prices that were previously only in the realm of data centres,” concluded Grier.